How does SwasthiyaSure assist with policy selection?
+
SwasthiyaSure provides insurance guidance through individually appointed insurance agents associated with ICICI Lombard, Niva Bupa and HDFC ERGO. Our advisors explain policy features, waiting periods, exclusions, hospital networks and claim conditions, helping customers evaluate available options based on their requirements and the information available.
Why shouldn't I just buy health insurance directly online?
+
While online portals offer quick digital checkouts, they cannot interpret intricate policy fine print—such as room rent proportionate deductions, disease-specific sub-limits, or strict disclosure nuances. More importantly, when medical emergencies occur, online portals do not provide dedicated local advocate support at hospital cashless admission desks.
How do you assist during hospital claim settlement?
+
We act as your personal claim advocate from the hour of admission. We review pre-authorization forms before submission, ensure accurate medical diagnosis documentation, liaise directly with hospital Third Party Administrators (TPAs), minimize non-medical deductions, and resolve insurer queries to ensure swift cashless clearance.
Can NRIs buy health or term insurance in India?
+
Yes. Non-Resident Indians (NRIs) and Pravasis worldwide can secure comprehensive health insurance for elderly parents in India or maintain domestic coverage for themselves during annual trips. Premium payments can be executed seamlessly via NRE/NRO banking or international cards, with FEMA and IRDAI compliance handled end-to-end.
What is the 36-month pre-existing disease (PED) rule introduced by IRDAI?
+
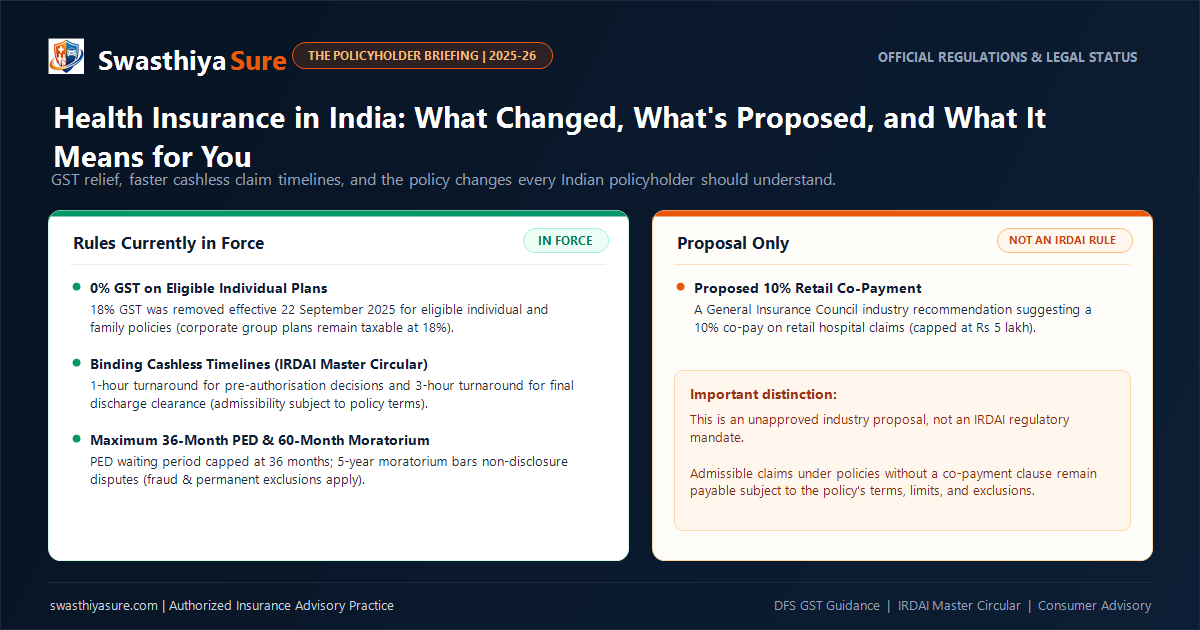
Under IRDAI Master Guidelines, the statutory maximum waiting period for Pre-Existing Diseases (PED) has been reduced from 48 months (4 years) to 36 months (3 years) across all retail health insurance policies in India. Furthermore, insurers can no longer contest a claim after 60 continuous months (5 years) of policy coverage, except in proven cases of established fraud.
Why is a super top-up policy better than increasing base sum insured?
+
A Super Top-Up policy provides massive additional coverage (such as ₹25 Lakhs to ₹1 Crore) at a fraction of the cost of increasing your base policy. It works by setting an aggregate deductible (e.g. ₹5 Lakhs) across the policy year. Your employer GMC or modest retail policy pays initial claims, and the super top-up absorbs any catastrophic hospital billing thereafter.
Do you charge consultation fees for policy advisory?
+
No. Our advisory consultations, existing policy check reviews, and claim guidance support are completely free of charge to individuals, families, and NRIs. As authorized intermediaries, advisor remuneration is standardized under IRDAI regulations by the respective insurers, meaning you pay the exact approved premium with zero markup or hidden advisory fees.